Suzano: Substantial Upside If Pulp Prices Normalize
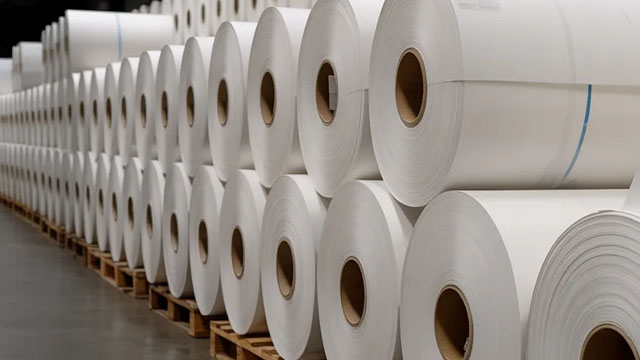
Suzano offers compelling long-term upside as the pulp cycle appears to be bottoming and supply curtailments accelerate. SUZ's lowest-quartile production costs and vertical integration enable resilience and strong margins even amid depressed pulp prices. New Chinese capacity and elevated debt make timing the recovery slightly harder; however, return potential makes it worthwhile.
Seeking Alpha10/6/2026Positive