Hormel: Undervalued And A Record Yield But Facing Growth Struggles
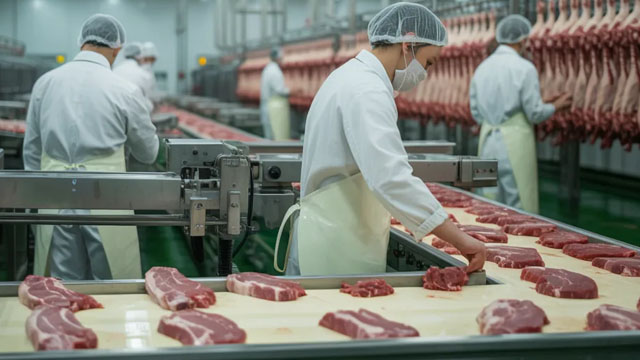
Hormel remains a 'hold' as persistent inflation, input cost pressures, and weak organic growth offset its undervaluation and strong dividend history. New management has streamlined HRL's portfolio, exited low-margin businesses, and is focusing international efforts on the Asia Pacific for higher growth potential. Despite a nearly 6% yield and 59-year dividend growth streak, HRL's dividend growth rate has slowed to ~1% with coverage concerns tied to volatile EPS and FCF.
Seeking Alpha9/28/2026Positive