VICI

VICI Properties Inc
NYSEREAL ESTATEREIT - DIVERSIFIED

Key Statistics

Market Cap
$27.30B
P/E Ratio
11.48
EPS
$2.16
Beta
0.65
52W High
$28.95
52W Low
$22.43
50-Day MA
$24.04
200-Day MA
$26.89
Dividend Yield
7.18%
Profit Margin
56.50%
Forward P/E
8.40
PEG Ratio
—

About VICI Properties Inc

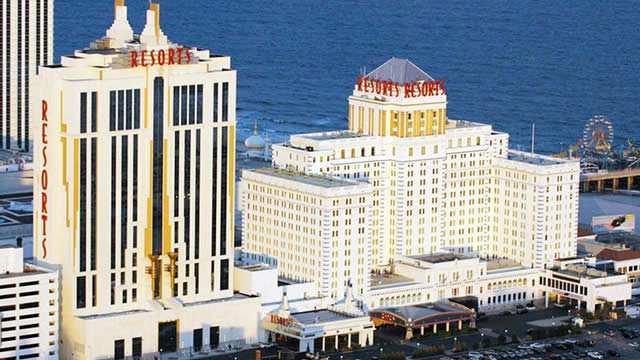
VICI Properties is an experiential real estate investment trust that owns one of the largest portfolios of market-leading gaming, hospitality and entertainment destinations, including the world-renowned Caesars Palace.

Official WebsiteUSAFY End: December

Fundamentals

Revenue (TTM)$4.16B
Gross Profit (TTM)$4.13B
EBITDA$3.22B
Operating Margin52.80%
Return on Equity8.28%
Return on Assets4.25%
Revenue/Share (TTM)$3.84
Book Value$26.35
Price-to-Book0.96
Price-to-Sales (TTM)6.57
EV/Revenue10.9
EV/EBITDA14.02
Quarterly Earnings Growth (YoY)-56.30%
Quarterly Revenue Growth (YoY)5.80%
Shares Outstanding$1.10B
Float$1.10B
% Insiders0.28%
% Institutions98.07%

Historical Volatility

HV 10-Day
34.88%
HV 20-Day
30.42%
HV 30-Day
26.03%
HV 60-Day
21.75%
HV Rank
96.0%

Volatility is currently expanding

Analyst Ratings

Consensus ($29.78 target)
4
Strong Buy
12
Buy
9
Hold

Latest News

November Buy: 6 IDEAL S&P 500 'Safer' Dividend Dogs

Six S&P 500 'safer' high-yield dividend stocks—Regions Financial, Ford, AT&T, Pfizer, Verizon, VICI Properties—currently offer attractive buy signals based on free cash flow yields. Analyst projections for the top ten S&P 500 dividend dogs indicate potential net gains of 14.54% to 40.07% by November 2027, with an average estimated gain of 27.42%. Dividend dog strategy favors stocks where annual dividends from $1,000 invested exceed single-share prices and free cash flow yields surpass dividend yields.

Seeking Alpha11/6/2026Positive
3 Dirt Cheap Dividend Stocks to Buy in November 2026

AT&T, Novo Nordisk, and Vici Properties have struggled this year but remain high-quality investments. Their valuations are incredibly low, giving investors the potential to benefit from high dividends and strong long-term returns.

The Motley Fool11/3/2026Positive
VICI Properties: $2 Billion Says Mr. Market May Be Wrong (Rating Upgrade)

VICI Properties trades at a deep discount—9.5x 2026 AFFO versus a 14.5x historical average—despite iconic assets and resilient contractual cash flows. I have a Strong Buy rating, targeting $30 per share and >30% total return potential, supported by a 7.7% dividend yield and multiple expansion opportunity. VICI's $2B share repurchase authorization, robust balance sheet (4.8x net debt/EBITDA), and well-covered dividend (74% payout ratio) enhance capital allocation flexibility.

Seeking Alpha11/3/2026Positive
5 October Dividend Raises Up To 8.8%, Yields Up To 7.5%, 2 Buy Recommendations

VICI Properties and W. P. Carey are identified as the most undervalued October dividend raisers in the Rose Income Garden portfolio. VICI offers a 7.52% yield, is rated a buy due to undervaluation, and is expanding beyond Las Vegas into broader experiential real estate. Altria, Mondelez, and Philip Morris are quality dividend growers; MO and PM are considered holds due to valuation, while MDLZ is a watch for lower entry.

Seeking Alpha11/3/2026Positive
VICI Properties: An Encouraging Q3, But Still Not Enough To Buy

A concern for VICI Properties Inc. has been its high tenant concentration. I expect some improvement on this matter in Q4 as the tenant base is broadening out via lease severances. VICI Properties recorded a $458M noncash credit loss provision, including $313M attributable to key tenant Caesars Entertainment, highlighting tenant credit risk and reducing reported net income. VICI Properties refinanced its 2026 debt maturities, reducing immediate refinancing uncertainty but raising borrowing costs, with another $1.5 billion maturing in 2027.

Seeking Alpha11/2/2026Negative
VICI Properties Has Been Rehearsing For Caesars, One Lease At A Time

VICI Properties is rated a Buy, offering a secure 7.5% yield amid uncertainty from Caesars Entertainment's leveraged buyout. VICI's recent lease transitions—executed without rent loss—demonstrate management's ability to mitigate tenant risk and preserve cash flows. Three scenarios for the Caesars lease—fix, partial sale, or full sale—are all manageable for VICI, with tenant concentration risk a key focus.

Seeking Alpha11/2/2026Positive
2 Strong Buy REITs Following Their Q3 Earnings

Two beaten-down REITs surprised investors with stronger-than-expected quarterly results. Dividend hikes and share buybacks signal confidence despite market concerns. Deep discounts and improving fundamentals could fuel substantial upside.

Seeking Alpha11/2/2026Positive
VICI Properties: Priced Like Las Vegas Is Ending, Paying Me A 7%+ Yield To Wait

VICI Properties is upgraded to a strong buy, driven by robust fundamentals despite recent underperformance and sector headwinds. VICI trades at a compelling 9.5x forward AFFO and offers a well-covered 7.8% yield, supported by growing AFFO and a conservative 75% payout ratio. A $2 billion share repurchase program and continued AFFO guidance raises underscore management's confidence in long-term value creation.

Seeking Alpha11/2/2026Positive

Turn research into an automated options-selling system

Tiblio connects your broker and runs your put-and-call-writing strategy for you — on VICI and any ticker you trade — then tracks every position and per-strategy win rate.

See how it works

More REAL ESTATE Stocks

Data last updated: 11/7/2026